Credit card & ACH processing · Utah
Payment processing, priced by a CPA.
You know your rate. What you actually paid is a different number, and the gap between the two is where processors make their money.
Send us a recent statement and we'll mark it up line by line, the way an accountant would. No cost, no obligation.
You're likely paying more for merchant processing than you think.
Illustrative sample. The three flagged lines are the ones that never come up on the sales call.
What most people who call us are looking for, and what they're tired of. If one of these is you, keep reading.
A real person in the U.S. handles your account.
From the first call to your first deposit
Account frozen after a strong month.
A volume spike or one large ticket
Quoted 2.6%. The statement says 4.1%.
Downgrades, padded interchange, junk line items
A ticket number and no reply.
An offshore queue and nobody who knows you
Start here
Four layers on every statement.
Two are fixed and nobody can change them. The other two are negotiable, and that's the whole conversation.
Interchange Fixed
Goes to the bank that issued your customer's card. Visa and Mastercard publish these rates publicly and every processor pays the identical amount. Nobody gets you a discount here.
Assessments Fixed
The card networks' own cut. Also identical everywhere, also non-negotiable.
Processor markup Negotiable
What your provider adds on top. This is the number a rate quote is usually describing, and it's the one that gets quoted low and drifts up.
Everything else Often removable
Monthly minimums, PCI fees, statement fees, batch fees, downgrade penalties from transactions that weren't submitted with the right data. This is where most of the surprise lives, and a fair amount of it is fixable by changing how transactions are processed rather than by switching providers.
What a statement review turns up
What the markup finds.
Four examples of what a review typically uncovers. Same method every time: total fees divided by total volume, before and after.
Auto repair shop
About $60,000 a month in card volume
Fleet cards were downgrading because the invoices went through without Level II data.
Restaurant
About $90,000 a month in card volume
A tiered plan was sending most rewards cards into the most expensive bucket.
Med spa
About $45,000 a month in card volume
Monthly, PCI, and statement fees that added up to more than the markup itself.
Wholesaler
About $150,000 a month in card volume
Business cards keyed in without tax or PO data, so every one of them downgraded.
Examples based on common statement findings, not individual client results. Your numbers depend on your card mix, ticket size, and volume.
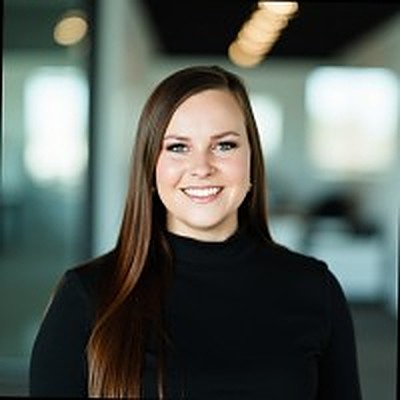
Built by an accountant.
I got tired of reading these statements for my clients.
Firm accounting and fractional CFO work taught me that most small business owners know exactly what they bring in and have very little idea where it goes.
Processing fees turned up in almost every engagement. An owner would tell me they were paying 2.6%, and then I'd open the statement and find something closer to three and a half, buried in line items nobody had walked them through when they signed.
My sister Ashley and I started Opal after I'd run that math for client after client. I wanted a processor where the person setting your pricing understands a P&L, and the proposal shows what you'll keep.
If I wouldn't put a client on it, we don't sell it.
What that changes
Where that shows up.
All three come from having a CPA set your pricing.
No surprise freezes
A good month should not trigger a hold. If growth or a large ticket needs documentation, you hear about it before anything touches your funds.
Dual pricing done right
Two prices at checkout, cash and card, so the fee sits where it belongs, and a straight explanation of the rules that come with it.
Payments that reconcile
Transactions sync to QuickBooks and Xero. The deposits on your bank statement match the entries in your books without anyone keying them in twice.
How it moves
A payment should be boring.
A customer taps a card, the gateway routes it, and the money lands in your account on schedule. Plenty can go wrong between those steps, and our job is to keep it from happening.
Every Opal account runs on NMI's payment gateway, the same infrastructure behind more than a million merchants.
For accountants & fractional CFOs
Now you have an answer.
Your client asks what to do about processing fees. Send us the introduction and step out. We handle the analysis, the proposal, underwriting, and onboarding. You keep the relationship.
You make a warm introduction
Email, text, or the referral formWe handle everything after that
Analysis, proposal, underwriting, onboardingYour client activates and starts processing
No monthly involvement, no compliance exposure for youYou get paid
Tiered bonus by client volumeFree statement review
Send us last month's statement.
We'll mark it up the way an accountant would and show you your real effective rate: total fees divided by total volume.
No cost, no contract, and no salesperson calling you six times. If you're already in a good deal, we'll tell you that.
We read it
Every line, including the ones nobody explained.
We mark it up
Annotated and sent back, with the removable fees flagged.
We tell you if it's worth switching
If we can't beat it, we say so.
Woman-owned and based in Utah.
We built Opal because the businesses we watched get declined, frozen, or overcharged were usually the ones with the least room to push back. A business that can't take cards can barely operate, and that call shouldn't come down to a category code.